VA home buying · Nevada & Placer Counties
Your first VA home. Or your next one.
Understand your benefit, plan your cash and explore your next move with a fellow U.S. Air Force veteran.
Get the 24-page VA Home Buying Guide, including an entitlement walkthrough and a worksheet for your lender conversation.
Get my VA home buying guide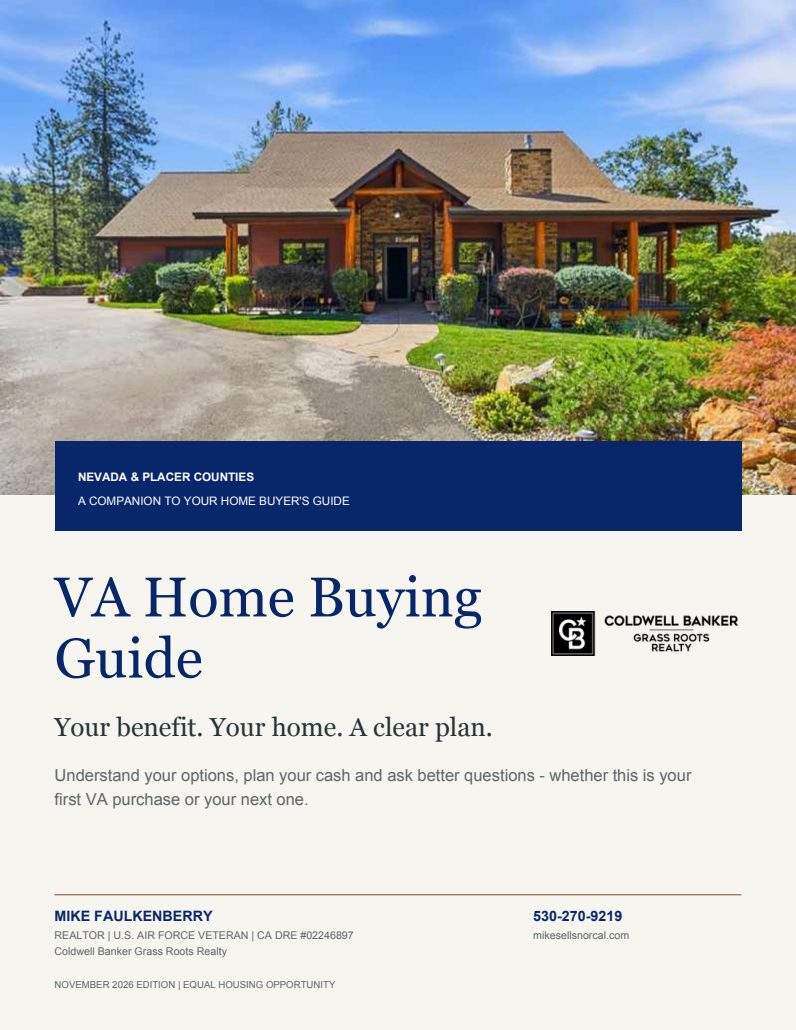
A clear plan for the benefit you earned
Inside your VA guide
- Eligibility and your Certificate of Eligibility
- Cash to close and the funding fee
- Entitlement, another VA purchase and restoration
- Appraisal versus inspection and foothill property questions
- Representation, offers and closing
The worksheet on page 22 helps you record the next questions to take to your lender and escrow.
Use this VA companion alongside my general Home Buyer’s Guide.
Where should I send your copy?
Enter your name and email, then review the contact consent before submitting. No phone number or website account is required.
Your VA guide is ready.
Download it now. Your emailed copy will normally arrive within a few minutes; check your spam folder if needed.
A note from Mike
The benefit that opened the door for me.
I bought my first home with a VA loan, no down payment and about $2,500 from my savings. That purchase got me into homeownership. I later used VA financing to buy another primary residence.
I did not fully understand entitlement when I bought and sold that first home. Today, I help buyers ask the questions I wish I had understood earlier.
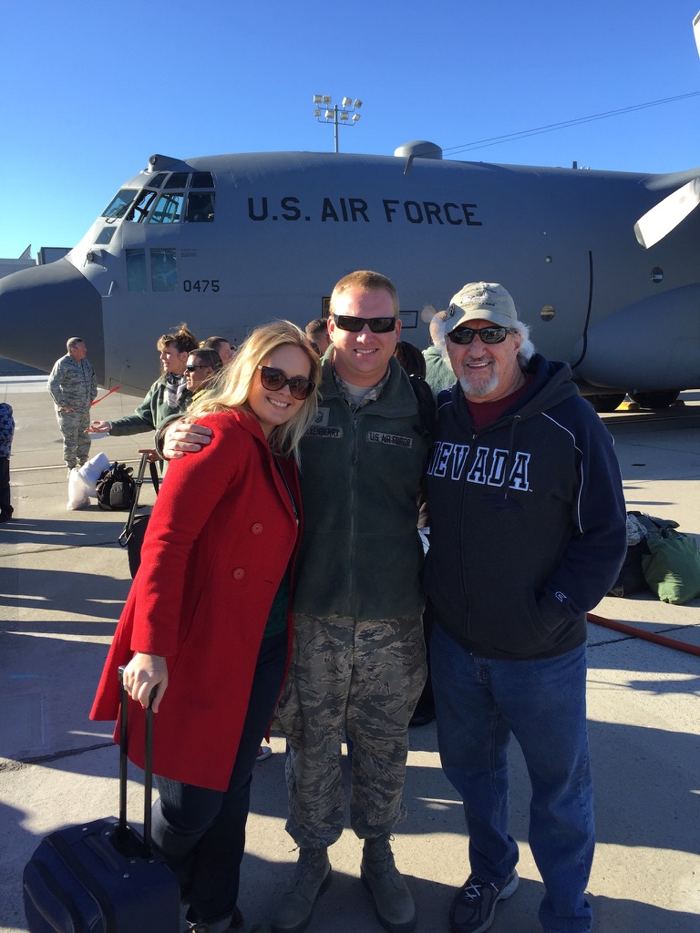
I’m a Nevada County native and a 15-year U.S. Air Force veteran who separated as a Master Sergeant. My work connects your plans, your lender’s numbers and the property you want to call home.
My first-purchase costs are a personal experience, not an estimate of your costs.
Understand the options
What your VA benefit may make possible
A possible zero-down purchase
When eligibility, entitlement, value and lender requirements support it. Plan for the other cash needed, too.
No monthly PMI
VA-backed loans do not require private mortgage insurance. Interest, taxes, insurance and other ownership costs still apply.
A reusable benefit
You do not have to be a first-time buyer. Prior use does not automatically prevent another VA purchase.
VA purchase-loan benefits · VA: using the benefit more than once (September 2026)
Compare actual offers with other programs you may qualify for. Some conventional programs permit less than 20% down; rates, fees, points and credits vary.
Already own a VA-financed home?
You may have more than one path.
You do not always have to sell or refinance your current VA loan before using VA financing for another primary residence. A current COE and lender review can show whether remaining entitlement supports the next purchase, whether a down payment is needed, and how both properties affect qualification.
Using remaining entitlement is different from restoring entitlement. Sale plus payoff, a qualifying substitution, and the one-time paid-off-but-retained option have different requirements. Pages 9–12 explain these choices with an illustrative calculation.
The new home must meet occupancy rules. Another VA loan is different from a loan to buy a vacation home or a property solely for investment.
VA eligibility and entitlement restoration · VA entitlement and loan limits · VA: using the benefit more than once (September 2026)
Plan the real cash and payment
No down payment is one part of the budget.
Ask for a current itemized estimate covering deposits, closing costs, prepaids, inspections, any broker fee you owe and a reserve after closing. For a purchase, the VA funding fee can be financed; other closing costs cannot simply be added to the VA loan.
| Purchase down payment | First-use funding fee | Later-use funding fee |
|---|---|---|
| Less than 5% | 2.15% | 3.30% |
| 5% to less than 10% | 1.50% | 1.50% |
| 10% or more | 1.25% | 1.25% |
Exemptions may apply. Have your lender verify your status and confirm the current schedule before closing. Financing the fee increases your balance and interest cost.
Checked November 4, 2026: VA funding fees and closing costs
Local property questions
Look beyond the listing.
For a foothill home, investigate the actual water source, septic system, legal access, private-road obligations, heating, roof, permits and equipment agreements. Obtain an address-specific insurance quote early. A listing that accepts VA offers is not a pre-approved property.
VA revised its Minimum Property Requirements in 2026. Ask your lender which current requirements apply and use qualified inspectors and specialists to investigate condition. An appraisal does not replace your inspections.
VA current Minimum Property Requirements, Chapter 12 · VA home-buying process and appraisal options · VA 2026 appraisal requirement update
VA questions, answered
Do I need to refinance my existing VA loan first?
Not always. A lender can review whether remaining entitlement, or remaining entitlement plus a down payment, supports another primary-residence purchase while the current VA loan stays in place. You must still meet occupancy and underwriting requirements. VA: using the benefit more than once (September 2026)
Does zero down mean nothing out of pocket?
No. You may still have closing costs, prepaids, appraisal or inspection expenses, a funding fee if not exempt, and other cash needs. Get an itemized estimate. The worksheet on page 22 helps organize the questions. VA funding fees and closing costs
How do I get my Certificate of Eligibility?
Request it through VA.gov, ask a lender to request it electronically, or use the applicable VA form. The service records needed depend on your situation; some requests need additional review. A COE is not loan approval. Request your Certificate of Eligibility
Is a VA appraisal the same as a home inspection?
No. An appraisal addresses value and minimum property requirements. An inspection evaluates condition within the agreed scope. VA strongly recommends a home inspection. VA home-buying process and appraisal options
Can a well, septic system or wood stove affect the purchase?
Yes. Have the lender and qualified professionals review the property-specific requirements, testing, records, condition and any repair conditions. Avoid blanket assumptions that every rural system or heating arrangement either qualifies or fails. VA revised its property requirements in 2026. VA current Minimum Property Requirements, Chapter 12
Can a seller pay my costs or buyer-broker fee?
You can request a contribution, but it is negotiated and not guaranteed. VA distinguishes ordinary closing-cost credits, concessions and buyer-broker charges. Have your lender review the amounts and classification before you rely on a credit. VA buyer-broker charges: Circular 26-24-14
Keep loan benefits and tax benefits separate.
A funding-fee exemption does not automatically mean you qualify for California property-tax relief. Nevada County has announced a disabled-veteran exemption change beginning with the January 1, 2027 lien date. Confirm eligibility, amounts and filing instructions with the assessor for the property’s county.
California BOE Disabled Veterans' Exemption · Nevada County: new exemption beginning in 2027
